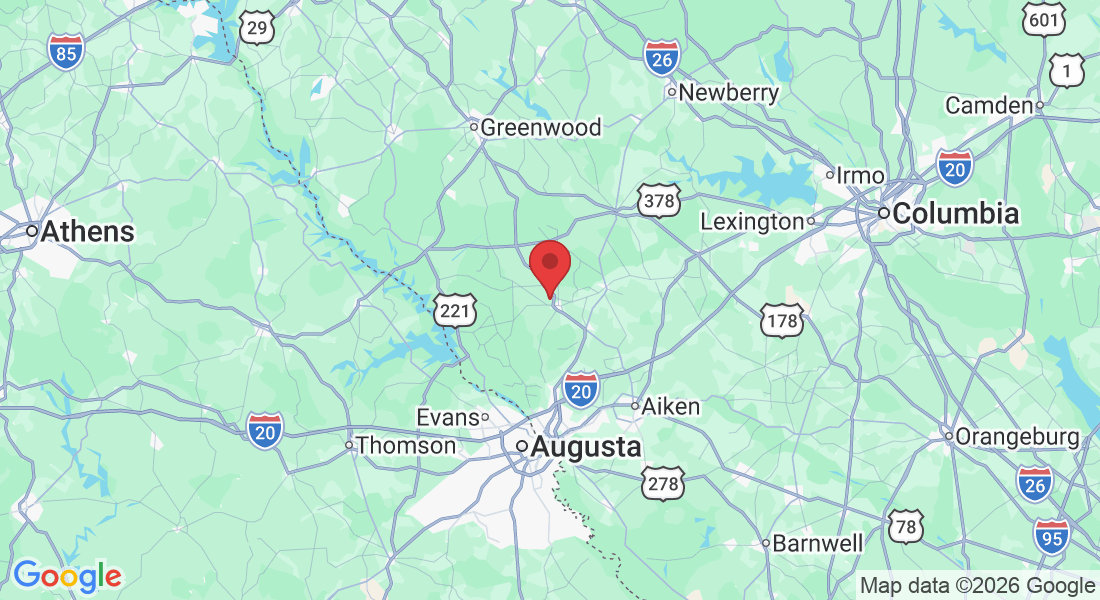
In the fantastic area of Edgefield County you’ll be in good company with around 29,521 residents with around 77% of those homeowners. With an average age of 43, the residents of Edgefield County are well established, made up of families of all age groups. Though fairly kicked back throughout the week, during weekends and holidays, you can see a lot more activity and excitement. Over the recent months roughly 195 homes have been sold with an average sold price of $288,081. That is a decrease of $32,872 from the previous period.
Want the full market report for Edgefield County?
We want to ensure that you have all the information needed to make the best decisions when it comes to your home goals. When you enter your info below you will get instant access to the area's latest market report, complete with sales and demographic trends.
Local News & Advice
Read helpful resources and articles related to the area.
How to Avoid Paying Two Mortgages When Moving Up in Augusta, GA
You need a bigger home.
But you already have a mortgage.
That can lead to one of the biggest worries Move-Up Sellers have:
“What if we end up paying for two houses at the same time?”
It is a fair question.
You may need the money from your current home to help buy the next one.
You may also be worried about carrying two mortgage payments, two utility bills, two insurance costs, and the other expenses that can come with owning two homes.
For Augusta-area homeowners, the answer starts with planning.
There are several ways a move can be structured, and each has different benefits and risks.
Here are some options to discuss before you start shopping for your next home.
1. Start With Your Current Home
It is easy to begin a move-up search by looking at bigger homes online.
But if avoiding two mortgages is important to you, start with the home you already own.
Ask:
What could my current home sell for?
What do I still owe?
How much equity might I have?
What might be left after selling expenses?
What does my home need before listing?
How quickly could we be ready to put it on the market?
These answers help you understand what you are working with.
Your current home is not a separate problem to solve later.
It is part of the same move.
2. Talk With Your Lender Before Shopping
Your Realtor can help you plan the real estate side of the move.
Your lender can help you understand the financing side.
Talk with your lender before you make an offer on the next home.
Explain that you own a home and want to avoid carrying two mortgages if possible.
Ask questions such as:
Do I need to sell my current home before I can buy?
Can I qualify while I still own my current home?
How will my current mortgage affect my next loan?
How much cash will I need for the next purchase?
Do I need proceeds from my current sale for the down payment?
What happens if one closing date changes?
Knowing these answers early can help you choose a better strategy.
3. Option One: Sell Your Current Home First
One of the clearest ways to reduce the chance of carrying two mortgages is to sell your current home before completing the next purchase.
This may give you:
A clearer idea of your sale proceeds
Access to money from the sale
One mortgage instead of two
A simpler financial picture
But there is a challenge.
Where will you live if you have not found the next house yet?
You may need to consider:
Temporary housing
Staying with family
Short-term rental options
Storage
Moving twice
For some families, the financial comfort of selling first may be worth the extra moving steps.
For others, temporary housing may be difficult.
That is why your family's needs matter.
4. Option Two: Coordinate the Sale and Purchase
Another possibility is trying to coordinate your current sale with your next purchase.
The goal is to have the transactions happen close together.
In some situations, a Move-Up Seller may sell the current home and then complete the next purchase on the same day or within a short period.
This can sound simple.
But it takes planning.
There may be:
Two sets of contracts
Two closing schedules
Two lenders
Title work
Inspections
Appraisals
Moving plans
Several people working on deadlines
A change in one transaction can affect the other.
That is why good communication matters.
Your Realtor, lender, closing professionals, and other people involved need to understand the plan.
5. Understand Home Sale Contingencies
If you find the next home before your current home sells, a home sale contingency may be something to discuss.
In simple terms, a home sale contingency can make your purchase depend on the sale of your current property.
The exact terms matter.
The seller of the home you want to buy also has to consider whether the offer works for their plans.
Your current home's status can matter too.
There can be a difference between:
Your home is not listed yet
and
Your home is already under contract and moving toward closing.
A contingency can be one tool for coordinating a move, but it does not remove the need for careful planning.
6. Get Your Starter Home Ready Before You Find the Next One
One common mistake is waiting until you find the next house before thinking about preparing the current one.
Then everything becomes urgent.
Repairs.
Cleaning.
Photos.
Decluttering.
Packing.
Listing.
Showings.
All while you are trying to buy another home.
Instead, prepare early.
You can start by:
Making needed basic repairs
Decluttering
Packing things you do not use
Deep cleaning
Improving basic curb appeal
Talking about pricing
Gathering important home information
You may not be ready to list today.
That is okay.
Being ready can still give you more options when the right next home appears.
7. Know Whether You Need Your Equity for the Next Purchase
This is a big piece of the puzzle.
Your current home may have equity.
But if the home has not sold, that does not mean you already have the sale proceeds available.
Ask yourself:
“Do we need money from this sale to complete the next purchase?”
If the answer is yes, the order of the transactions becomes very important.
You may need the current home to sell before you can complete the next purchase.
Or your lender may be able to explain other financing choices that could apply to your situation.
Do not assume the equity will automatically be available when you need it.
Talk through the timing before making an offer.
8. Build Your Next-Home Budget Around Real Numbers
It can be exciting to see how much home you may qualify to buy.
But qualifying for a loan and feeling comfortable with the payment are not the same thing.
Look at the bigger picture.
Your next home may come with changes in:
Mortgage payment
Property taxes
Homeowners insurance
Utilities
Maintenance
HOA fees, when applicable
Yard care
Other household expenses
If your goal is to avoid financial pressure during the move, choose a next-home budget that works for your family.
More house should give you more useful space.
It should not create a monthly payment that makes everything else harder.
9. Have a Backup Plan for Closing Delays
Even a carefully planned move can hit a delay.
A closing date may change.
A lender may need another document.
An appraisal may take time.
A repair may need attention.
A buyer's situation may change.
If your plan depends on one sale closing before another purchase, ask:
“What happens if the first closing moves?”
Talk through this before closing week.
Your backup plan might involve changes to moving arrangements, storage, temporary housing, or other parts of the schedule.
The specific options depend on your contracts and situation.
The important part is knowing what you would do if the timing changes.
10. Do Not Assume Buying First Is the Easiest Choice
Buying the next home first can sound easier.
You get the keys.
You move.
Then you sell the old house.
From a moving standpoint, that may feel comfortable.
Financially, it can be a different story.
If your current home takes time to sell, you could have costs connected with both properties.
That may include:
Two mortgage payments
Two sets of utilities
Insurance costs
Property-related expenses
Maintenance on both homes
Buying first may still make sense for some homeowners.
But if avoiding two mortgages is one of your top goals, understand the financial risk before choosing that route.
11. Do Not Let Fear Force You Into the Wrong Next Home
There is another side to this problem.
You may sell your current home first because you want to avoid two mortgages.
Then you feel pressure to find the next house quickly.
That can lead to rushed decisions.
You may start thinking:
“We have to buy something.”
Your next home still needs to solve the reason you are moving.
Maybe you need:
More bedrooms
More storage
A larger yard
Another bathroom
A home office
A different floor plan
More garage space
A location that fits your daily life
Avoiding two mortgages is important.
So is buying a home that actually works for your family.
Your plan should consider both.
12. Decide How Much Timing Risk Feels Comfortable
There is no one move-up strategy that fits every family.
Some homeowners may be comfortable buying first.
Others may want the current home sold before taking the next step.
Some may try to coordinate both transactions closely.
Ask yourself:
How would we feel if we owned both homes for a short period?
Could our budget handle that?
How would we feel about temporary housing?
Could we handle moving twice?
Do we need our sale proceeds for the next down payment?
How specific is our next-home search?
Your answers can help you decide which type of inconvenience you would rather manage.
For some families, temporary housing may feel easier than carrying two homes.
For others, the opposite may be true.
13. Think of It as One Move, Not Two Transactions
Move-Up Sellers can get overwhelmed because it feels like they are managing two separate real estate deals.
Try looking at it differently.
You have one goal:
Move your family from the home that no longer fits into the home that does.
The sale and purchase are two parts of that plan.
A simple order might look like this:
Find out what your current home may be worth
↓
Estimate your possible sale proceeds
↓
Talk with your lender
↓
Prepare your current home
↓
Set your next-home budget
↓
Choose your selling and buying strategy
↓
Create a backup plan
↓
Coordinate the move
That gives you a roadmap before emotions and deadlines start taking over.
What Is the Best Way to Reduce the Chance of Two Mortgage Payments?
If avoiding two mortgages is a top priority, start by understanding whether your current home needs to sell before you buy.
Then compare your options.
Sell First
This may reduce the risk of owning two homes, but you may need temporary housing or another short-term plan.
Coordinate Both Transactions
This may reduce the gap between selling and buying, but the timing can be more complex.
Use a Contingent Offer When Appropriate
A home sale contingency may help connect your purchase to your current sale, depending on the contract and whether the seller accepts the terms.
Buy First
This may make the physical move easier, but it can create a period when you own both properties.
There is no single strategy that fits every Augusta Move-Up Seller.
The goal is to choose the plan that fits your finances, family, and comfort level.
Frequently Asked Questions
Can I sell my current home and buy another without paying two mortgages?
It may be possible to structure the timing so you reduce or avoid an extended period of owning both homes. The right approach depends on your financing, contracts, sale timing, and next purchase.
Should I sell my house before buying the next one?
Selling first may give you a clearer financial picture and reduce the risk of carrying two homes. The tradeoff is that you may need temporary housing if the next home is not ready.
Can I close on my old home and new home on the same day?
Closings may sometimes be scheduled close together or on the same day. Because one transaction may depend on the other, careful coordination and a backup plan are important.
What if I need my current home's equity for the down payment?
Talk with your lender early. If you need sale proceeds to complete the next purchase, that can affect the order and timing of your transactions.
What happens if my current home sale is delayed?
The answer depends on your contracts, financing, and closing plans. Ask about possible delays before signing so you understand what options may be available.
Should I start looking for my next house before listing my current one?
You can begin learning about your next-home options while preparing your current home. Understanding both sides can help you create a plan before making an offer.
Meet Sherry Sanders
For Sherry Sanders, moving up is not about juggling two houses and hoping the dates work out.
It is about building one clear plan for the entire move.
As a former educator in both Richmond County and Columbia County, Sherry brings a teacher's approach to real estate.
She helps homeowners break a complicated move into smaller steps, understand their choices, and ask important questions before deadlines arrive.
Her deep community roots and strong relationships with local businesses and service providers can also provide helpful resources throughout the selling, buying, and moving process.
Backed by more than two decades of local sales and leadership experience in real estate, Sherry specializes in helping Augusta-area Move-Up Buyers and Sellers connect the sale of the home they have with the purchase of the home they need next.
If paying for two homes is one of the things keeping you from moving up, start with a plan before you start house hunting.
Thinking about selling your current home and moving up in Augusta or the CSRA?
📞 Call Sherry Sanders at 706-877-7005 / 888-959-9461
🌐 Visit Sherry Sanders Realtor: sherrysandersrealtor.com
#SoldOnSherry